The Hidden Cost of Comfort: How Your Hospital Room Choice Can Halve Your Insurance Payout
- Nishadil
- October 16, 2026
- 0 Comments
- 5 minutes read
- 11 Views
- Save
- Follow Topic
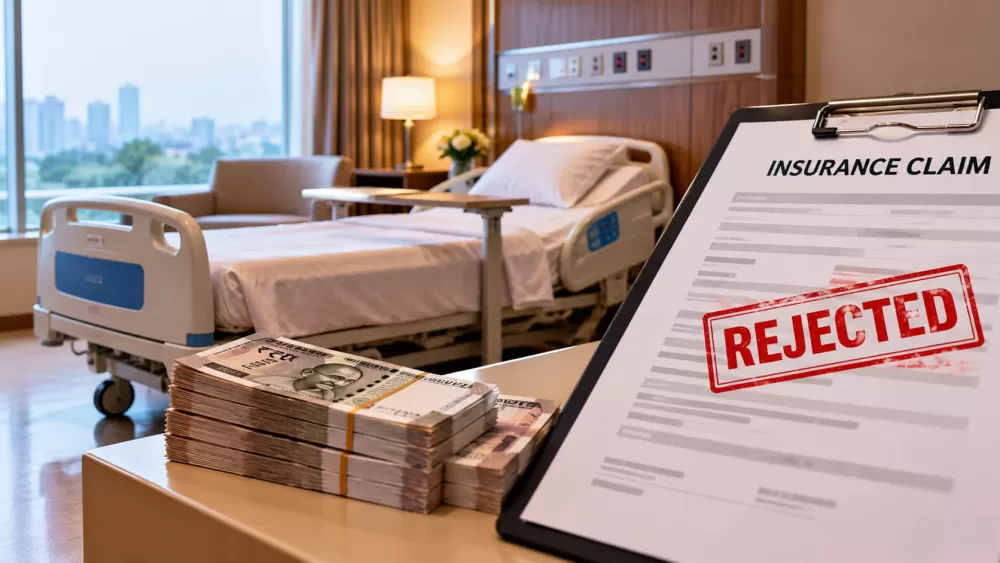
Beware the Room Rent Clause: Why a 'Better' Hospital Room Can Cut Your Entire Health Insurance Claim
Choosing a hospital room beyond your policy's daily limit can trigger a 'proportionate deduction,' slashing your entire health insurance claim, not just the room rent difference. Understand this crucial clause to avoid unexpected out-of-pocket costs.
We've all been there, perhaps in a moment of stress or a simple desire for comfort: choosing a slightly nicer hospital room, thinking it's just a small upgrade, maybe a few extra hundred rupees a day. "My insurance will cover most of it," you might think, perhaps even reassuringly. But here's a startling truth many only discover too late: that seemingly minor decision can actually slash your entire health insurance claim, leaving you with a shockingly large out-of-pocket bill. It’s a hidden clause, often tucked away in the fine print, known as "proportionate deduction," and it’s far more impactful than just the room rent difference.
So, how does this even happen? Well, most health insurance policies come with what's called a "room rent limit." This is the maximum amount your insurer is willing to pay for your hospital room each day. It's often expressed as a percentage of your total sum insured – say, 1% for a regular room or maybe 2% for an ICU stay. For instance, if you have a ₹5 lakh policy, your daily room limit might be just ₹5,000. Sounds perfectly reasonable, doesn't it? But what if the only available rooms at your chosen hospital start at ₹7,000 or even ₹10,000? That's precisely where things get tricky, and costly.
Now, this is the really critical part, and it's where the financial surprise often hits hardest. If you decide to go for a room that costs more than your policy's daily limit, the insurance company doesn't just ask you to pay the difference in room rent. Oh no, it goes much, much further. They apply something called a "proportionate deduction" to your entire hospital bill. Why, you ask? Because hospitals, you see, often operate on a tiered billing system. The fancier the room you pick, the higher the charges tend to be for almost everything else – surgeon's fees, anesthesiologist's charges, operating theater usage, and even those daily doctor consultations. These costs are frequently pegged directly to the room category you've chosen.
Let's paint a clearer picture with an example. Imagine your policy covers ₹3,000 a day for a room, but you opt for a ₹6,000 a day room – perhaps it was the only one available, or you simply wanted that extra bit of comfort. That's double your limit, right? Well, your insurer might then decide to pay only 50% of your entire hospital bill. Yes, you heard that correctly. If your surgery alone costs ₹100,000, and your room choice triggered a 50% deduction, the insurer would only cover ₹50,000 of that surgery cost, alongside all the other related expenses. We've seen real-world cases where a total bill exceeding ₹3.5 lakh resulted in nearly half being deducted, leaving the policyholder to shell out a massive sum themselves. It's a truly eye-opening, and often frustrating, experience during an already difficult time.
It’s important to understand which parts of your bill are vulnerable to this deduction. Generally, anything directly or indirectly linked to the room category will be affected: doctor visit charges, surgery fees, ICU charges, nursing care, and even those little daily consumables if they're bundled into the room rate. However, there's a small silver lining. Essential items like medicines, standalone medical consumables (think syringes, gloves), and standard diagnostic tests (like blood work or X-rays) are usually billed at a flat rate across all room types. These often get reimbursed in full, regardless of your room choice. But let's be honest, those usually represent a smaller, albeit necessary, portion of a major hospital bill.
So, what's a savvy individual to do to protect themselves? The absolute first step is to thoroughly check your health insurance policy documents. Look specifically for the "room rent clause," "daily room limit," and any explicit mention of "proportionate deduction." Understand what your policy truly allows before an emergency strikes. If you're currently shopping for insurance, or when it's time for renewal, actively seek out policies that offer "No Room Rent Capping." These policies explicitly state that they won't impose such limits, thereby sidestepping the entire proportionate deduction issue. It might cost a little more in premiums, sure, but it could save you a fortune and a headache during a difficult, vulnerable time.
Ultimately, the choice of a hospital room, seemingly innocuous, holds significant financial implications for your health insurance claim. Don't let a moment of comfort turn into a costly surprise. Be informed, read the fine print, and choose wisely. Your peace of mind, and your wallet, will definitely thank you for it.
Editorial note: Nishadil may use AI assistance for news drafting and formatting. Readers can report issues from this page, and material corrections are reviewed under our editorial standards.