A Glimpse into Tomorrow: The PM-SYM Pension for India's Small Traders
- Nishadil
- September 29, 2026
- 0 Comments
- 5 minutes read
- 14 Views
- Save
- Follow Topic
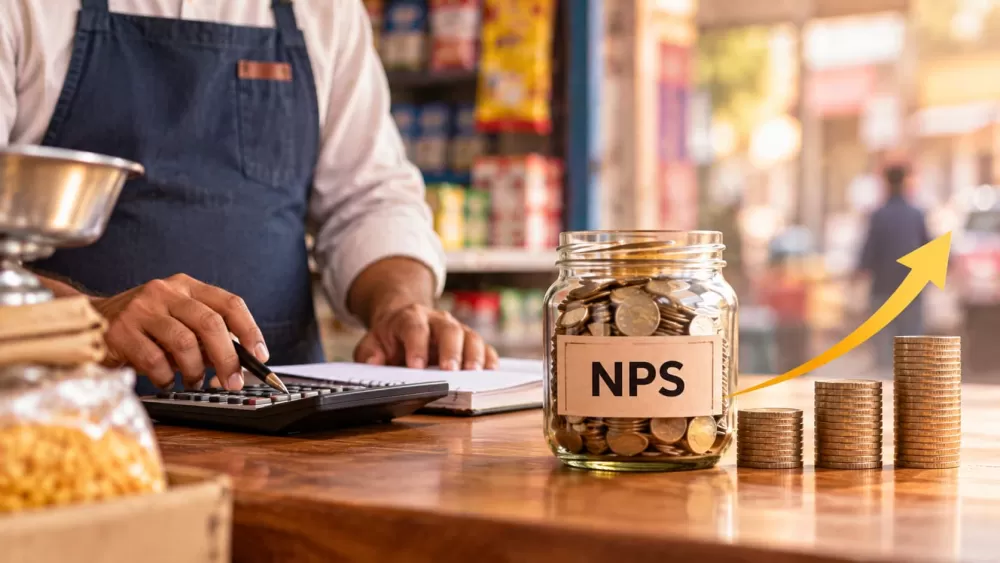
Is ₹3,000 Enough? India's Labour Ministry Urges Small Traders to Secure Their Future with the PM-SYM Pension
The Ministry of Labour and Employment is actively encouraging small business owners and shopkeepers across India to enroll in the National Pension Scheme for Traders (PM-SYM), offering a modest ₹3,000 monthly pension. But financial experts are raising questions about its real-world value over time.
Imagine a world where, after decades of hard work running your shop or small business, a steady stream of income awaits you in your golden years. That's precisely the vision the Ministry of Labour and Employment has been championing across India with its National Pension Scheme for Traders, affectionately known as PM-SYM. The push is on, urging the nation's countless small traders and shopkeepers to sign up for a promised ₹3,000 monthly pension once they hit 60. Sounds like a decent safety net, right?
Launched back in September 2019, this scheme – originally proposed as the Pradhan Mantri Laghu Vyapari Maan-dhan Scheme – aims to bring a bit of financial security to those who often operate without formal retirement benefits. We're talking about the backbone of our economy here: the small retail traders, the shopkeepers, and various self-employed individuals, often referred to as 'Vyaparis.' The key criteria? Your annual turnover needs to be up to ₹1.5 crore. It’s a thoughtful move, designed to cover a vast segment of our informal workforce.
So, who exactly can jump on board? If you're aged between 18 and 40, you're in the right age bracket. There are a few important caveats, though. If you're already contributing to schemes like EPFO, ESIC, NPS, or even the PM-SYM itself (for other categories), or if you're an income taxpayer, then this particular variant of the scheme isn't for you. It's truly geared towards those who might otherwise fall through the cracks of organized social security.
The contribution model is rather simple and quite appealing, actually. It's voluntary, meaning you decide to join. And it's contributory, but with a twist: the Central Government matches your contribution rupee for rupee. Depending on your age when you enroll, your monthly payment can range anywhere from a manageable ₹55 to ₹200. Let's say you're 29; your contribution would be ₹100, and the government would chip in another ₹100. It’s a 50-50 partnership for your future.
Now, what happens if, heaven forbid, something happens to the beneficiary? Well, the scheme does offer a bit of solace there too. Should the enrolled individual pass away, their spouse isn't left entirely without support. They're entitled to receive 50% of the pension, which works out to ₹1,500 per month, as a family pension. It's not a huge sum, but it's something, offering a small cushion during difficult times.
Getting enrolled is surprisingly straightforward. You can visit one of the 3.50 lakh Common Service Centres (CSCs) spread across the country – these are pretty much everywhere now – or, if you prefer the digital route, you can even self-enroll online at www.maandhan.in. It’s designed to be accessible, removing as many hurdles as possible for potential beneficiaries.
However, and this is where the conversation gets a little more nuanced, financial experts have raised some pertinent questions about the long-term efficacy of this ₹3,000 monthly payout. Think about it: ₹3,000 today feels very different from what ₹3,000 will feel like twenty or thirty years down the line. Vijay Kuppa, CEO of InCred Money, along with Manish P. Hingar, Founder and CEO of Fintoo, both echo this sentiment quite strongly. They highlight a crucial point: inflation.
They argue, quite convincingly, that a fixed ₹3,000 pension, without any adjustment for the rising cost of living, will likely be grossly inadequate for a comfortable retirement. To put it into perspective, if inflation runs at, say, 6% annually, that ₹3,000 you receive 25 years from now could have the purchasing power of roughly just ₹700 in today's money. It's a harsh reality that simply can't be ignored when planning for one's golden years. This pension, they suggest, might barely cover basic groceries, utilities, or perhaps a tiny portion of rent.
Moreover, the scheme doesn't offer a lump-sum payout at age 60, which many might hope for to cover larger expenses or initial retirement costs. And, critically, it doesn't extend coverage to the beneficiaries' children. So, while it offers a base, a foundation if you will, it's certainly not a comprehensive retirement solution. Experts universally advise viewing PM-SYM as a 'small base' – a starting point, perhaps, but one that absolutely needs to be supplemented with other savings and investment strategies.
In essence, while the Labour Ministry’s efforts to bring social security to India's vast network of small traders are commendable and provide a much-needed initial step, prospective enrollees should go into it with open eyes. The PM-SYM scheme offers a foundational safety net, a welcome hand for many. But for a truly secure and comfortable retirement, a more holistic and inflation-aware financial plan is undoubtedly essential. It's a piece of the puzzle, not the whole picture.
- India
- Business
- News
- BusinessNews
- Inflation
- FinancialPlanning
- LabourMinistry
- NpsTraders
- NpsForSelfEmployedBusiness
- 000MonthlyPension
- NpsForShopkeepers
- NpsPensionScheme
- LabourMinistryNps
- TradersPension
- PensionSchemeForShopkeepers
- PmSym
- SmallTradersPension
- RetirementIndia
- ShopkeepersScheme
- VyaparisPension
Editorial note: Nishadil may use AI assistance for news drafting and formatting. Readers can report issues from this page, and material corrections are reviewed under our editorial standards.